

Property insurance is designed to protect homeowners, businesses, and property owners from financial losses caused by unexpected events such as fire, theft, storms, or other covered risks. However, the effectiveness of this protection depends largely on whether the property is insured for its correct value. When a property is insured for less than its actual value, it is considered underinsured.
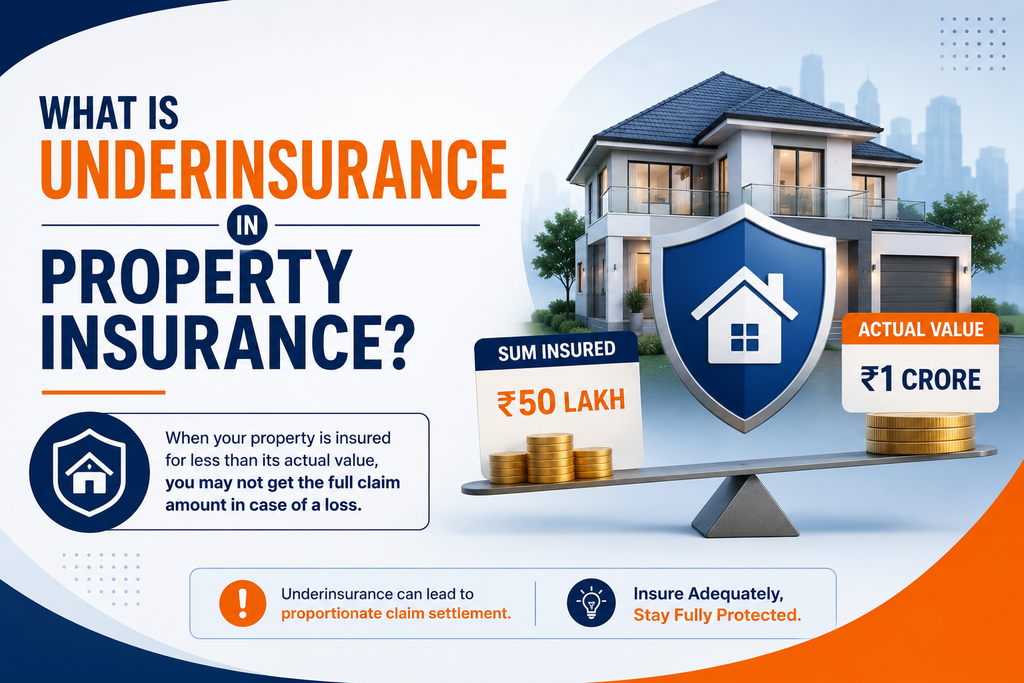
Underinsurance is a common issue that can significantly reduce the amount payable during a claim, leaving policyholders responsible for a portion of the loss.
Understanding Underinsurance
Underinsurance occurs when the sum insured stated in a property insurance policy is lower than the actual cost required to rebuild, repair, or replace the insured property.
For example, if a property has a replacement value of ₹1 crore but is insured for only ₹70 lakh, the property is underinsured by 30%. While this may reduce insurance premiums, it can create serious financial consequences when a claim arises.
Why Does Underinsurance Happen?
Several factors can lead to underinsurance:
Incorrect Property Valuation
Property owners may underestimate the actual replacement cost of their building, machinery, equipment, or contents.
Rising Construction Costs
Construction materials, labour charges, and rebuilding expenses often increase over time. If policy values are not updated regularly, coverage may become insufficient.
Failure to Review Policies
Many policyholders renew their insurance policies year after year without reassessing the property’s current value.
Cost-Saving Measures
Some individuals or businesses intentionally choose a lower sum insured to reduce premium costs, unaware of the potential impact on future claims.
Property Improvements
Renovations, extensions, and upgrades can increase property value. If these changes are not reported to the insurer, the existing coverage may no longer be adequate.
How Underinsurance Affects Claims
One of the most significant consequences of underinsurance is the application of the Average Clause.
The Average Clause allows the insurer to reduce the claim payout proportionately when the property is insured for less than its actual value.
Example
Suppose:
- Actual value of the property: ₹1 crore
- Sum insured: ₹75 lakh
- Loss suffered: ₹20 lakh
Since the property is insured for only 75% of its actual value, the insurer may pay only 75% of the admissible loss.
In this example:
₹20 lakh × 75% = ₹15 lakh
The remaining ₹5 lakh may have to be borne by the policyholder.
This reduction can occur even when the loss is partial and far below the total property value.
Risks Associated with Underinsurance
Reduced Claim Settlement
The most immediate consequence is receiving a lower claim amount than expected.
Financial Burden
Policyholders may need to arrange additional funds to repair or rebuild damaged property.
Business Disruption
For businesses, insufficient claim payments can delay recovery and affect operations.
Asset Protection Gaps
Important assets may remain inadequately protected against major losses.
How to Avoid Underinsurance
Conduct Regular Valuations
Property values should be reviewed periodically to ensure they reflect current replacement costs.
Consider Rebuilding Costs
Insurance should be based on rebuilding or replacement costs rather than market value alone.
Update Coverage After Improvements
Any renovations, additions, or major upgrades should be reported to the insurer.
Review Policies Annually
Annual reviews help ensure that coverage remains aligned with current property values and changing circumstances.
Seek Professional Guidance
Expert assessment can help determine appropriate coverage levels and reduce the risk of underinsurance.
Why Property Owners Should Pay Attention
Many policyholders discover they are underinsured only after filing a claim. By that stage, the financial impact can be significant. Proper valuation and regular policy reviews help ensure that insurance protection remains adequate when it is needed most.
Understanding the concept of underinsurance is particularly important for commercial properties, warehouses, factories, offices, residential buildings, and other high-value assets.
Final Thoughts
Underinsurance in property insurance occurs when the insured value of a property is lower than its actual replacement or rebuilding cost. While it may reduce premium expenses in the short term, it can result in substantially lower claim settlements due to the application of the Average Clause.
Property owners should periodically review their insurance coverage, reassess property values, and ensure that their policies provide adequate protection against potential losses.
If you are facing issues related to underinsurance, claim reductions, short settlements, claim disputes, or property insurance claim challenges, professional guidance may help you better understand your rights and available options.
Contact Us
Insurance Resolve
📞 +91 99103 52249
🌐 www.insuranceresolve.com
📧 help@insuranceresolve.com

