

Contents Insurance is a type of insurance that provides financial protection for the belongings and movable items kept inside a home, office, or other insured premises against specified risks.
Unlike building insurance, which primarily covers the physical structure of a property, contents insurance focuses on the items inside the property.
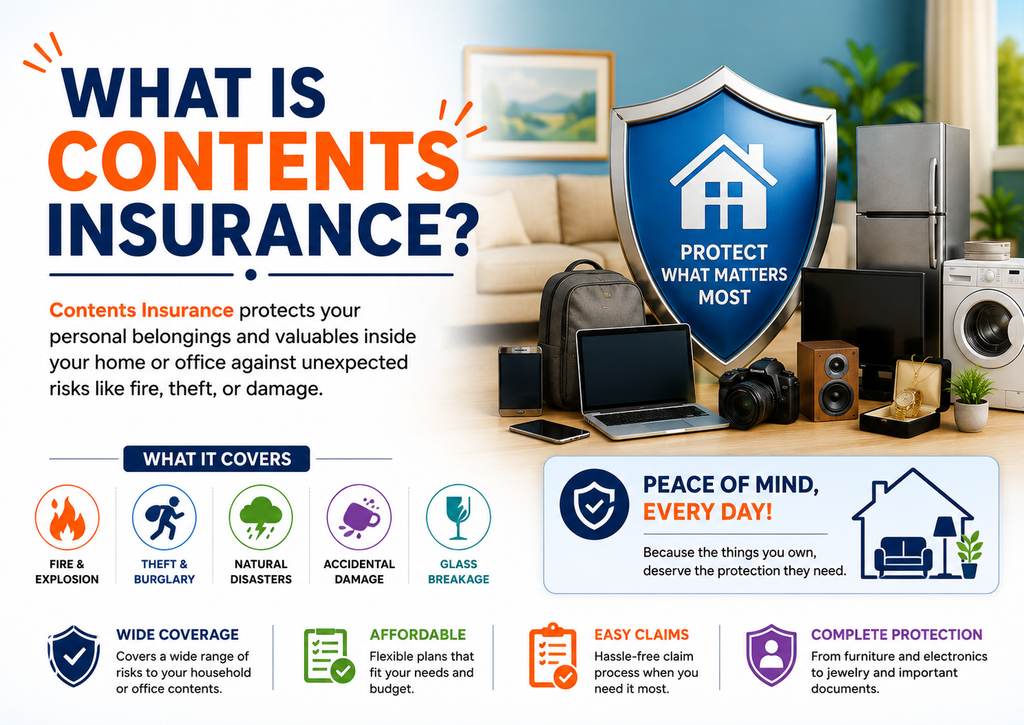
What Does Contents Insurance Cover?
The exact coverage depends on the policy, but contents insurance may cover items such as:
- Furniture
- Electronic appliances
- Television and computers
- Household equipment
- Personal belongings
- Clothing
- Kitchen appliances
- Certain valuable items
- Other specified contents
Coverage is subject to the policy’s terms, conditions, limits, and exclusions.
What Risks Can Contents Insurance Cover?
Depending on the policy, contents may be protected against specified risks such as:
Fire
Contents insurance may cover loss or damage to insured belongings caused by a covered fire incident.
Theft or Burglary
Some policies provide coverage for eligible contents lost or damaged due to covered theft or burglary.
Natural Events
Certain policies may cover specified natural events, such as storms, floods, or earthquakes, depending on the coverage selected.
Accidental Damage
Some contents insurance policies may provide coverage for accidental damage to insured belongings, subject to specific terms and conditions.
Contents Insurance vs Building Insurance
The two types of insurance protect different interests.
Building Insurance generally covers the physical structure of the property, such as walls, roof, floors, and permanent fixtures.
Contents Insurance generally covers movable belongings kept inside the property.
A property owner may require both types of protection depending on their circumstances and the insurance policy selected.
Why Is Contents Insurance Important?
Household and business belongings can represent a significant financial investment. Replacing furniture, electronics, appliances, and other possessions after a major covered event can be expensive.
Contents insurance can help reduce the financial impact of covered losses.
How Is the Value of Contents Determined?
The value of insured contents may be determined according to the valuation method specified in the policy.
Depending on the policy, valuation may consider replacement cost, current value, or another specified basis.
The sum insured should reflect the value of the contents intended to be insured, subject to the policy terms.
What Is Usually Not Covered?
Contents insurance does not cover every type of loss. Common exclusions may include:
- Normal wear and tear
- Gradual deterioration
- Poor maintenance
- Intentional damage
- Certain natural events
- Uninsured items
- Losses specifically excluded by the policy
The exact exclusions vary between insurance policies.
Contents Insurance Claim Problems
Policyholders may sometimes face contents insurance claim rejection, claim delay, short settlement, valuation disputes, or coverage disagreements.
The outcome of a claim can depend on the cause of loss, evidence of ownership, value of the contents, policy coverage, exclusions, and applicable conditions.
Get Help With Contents Insurance Claim Issues
If your contents insurance claim has been rejected, delayed, or short-settled, Insurance Resolve provides professional guidance for policyholders dealing with insurance claim and complaint-related concerns.
Insurance Resolve – Insurance Claim & Complaint Solutions
📞 Phone: +91 99103-52249
📧 Email: help@insuranceresolve.com
🌐 Website: www.insuranceresolve.com

